
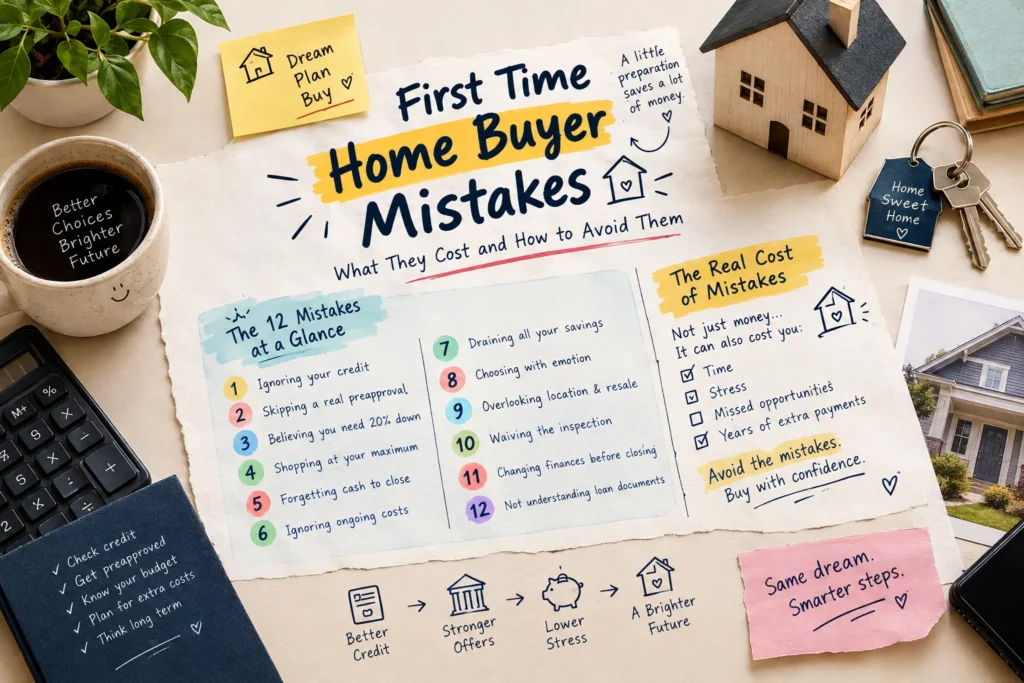
The most expensive of all first time home buyer mistakes is simple: buying at the top of what a lender will approve, then discovering that approval and affordability are two different things. Most other errors, from skipping a preapproval to forgetting closing costs, are smaller versions of the same problem. This guide ranks twelve mistakes by what they can cost you and shows how to avoid each one, using worked examples with clearly labeled assumptions. It is written mainly for buyers in the United States, and the rules differ in other countries. If you are working out how to buy your first home, read this before you make an offer.
General information only, not personal financial or legal advice. Rates, fees, limits and program rules change and vary by lender and location. Confirm details with a licensed lender, a HUD approved housing counselor or an official source.
Table of Contents
The Twelve Mistakes at a Glance
| # | Mistake | Main risk | Simple fix |
| 1 | Ignoring your credit | Higher rate or a denied loan | Check reports months ahead |
| 2 | Skipping a real preapproval | Offers rejected, surprises later | Get documents reviewed first |
| 3 | Believing you need 20 percent down | Waiting years for no reason | Compare low down payment options |
| 4 | Shopping at your maximum approval | A payment that strains you | Set your own budget first |
| 5 | Forgetting cash to close | Short of funds at the table | Budget every upfront cost |
| 6 | Ignoring ongoing costs | A payment that keeps growing | Price taxes, insurance, upkeep |
| 7 | Draining all your savings | No cushion after moving in | Keep a separate reserve |
| 8 | Choosing with emotion | Overpaying or compromising badly | Split needs from wants |
| 9 | Overlooking location and resale | A home that is hard to sell | Study the area, not just the house |
| 10 | Waiving the inspection | Large repair bills | Inspect and negotiate |
| 11 | Changing finances before closing | Loan approval can fall through | Freeze credit and income changes |
| 12 | Not understanding the loan documents | Costs you did not expect | Compare estimate to final figures |
First Time Home Buyer Mistakes Before You Start Looking
The preparation stage is where the costliest errors begin, because they shape every number that follows.
1. Ignoring Your Credit Until the Last Minute
Your credit report affects whether you are approved and what mortgage interest rate you are offered. Errors on a report are common, and fixing one can take weeks. Start at least three to six months before you plan to apply.
- Check for errors. Request your reports for free at AnnualCreditReport.com and read every account.
- Lower your balances. Paying cards down before the statement date can lower the balance that gets reported.
- Avoid new credit. New accounts add inquiries and can lower your score just when it matters.
2. Confusing Prequalification With Preapproval
A prequalification is a quick estimate based on information you provide yourself. A preapproval means a lender has reviewed your documents, such as pay records, bank statements and a credit check, and issued a letter stating how much it is willing to lend, subject to conditions. Sellers take a preapproval more seriously.
Many experts also suggest speaking to a lender before you contact an agent. That way you know your range before you fall for a home you cannot finance. Compare offers from more than one lender, because rates and fees can differ for the same borrower.
Next step: Ask two or three lenders for a Loan Estimate on the same day and compare the rate and total fees side by side.
3. Believing You Need 20 Percent Down
Putting 20 percent down helps you avoid private mortgage insurance on a conventional loan, but it is not a rule for buying. Some conventional programs accept as little as 3 percent down, FHA loans are designed for lower down payments and credit scores, and VA and USDA loans may need none for eligible buyers. Many states and cities also run down payment assistance programs.
The trade off is cost. A smaller down payment means a bigger loan, more interest and usually mortgage insurance. The right choice depends on your savings and your monthly budget, not on a single magic percentage.
| Loan type | Who it usually suits | Down payment note |
| Conventional | Buyers with solid credit and steady income | Low down options exist, insurance applies below 20 percent |
| FHA | Buyers with lower credit scores or smaller savings | Low minimum, with upfront and annual mortgage insurance |
| VA | Eligible service members, veterans and some spouses | Often no down payment required |
| USDA | Buyers in eligible rural areas, within income limits | Often no down payment required |
These descriptions are general. Minimums, fees and eligibility limits change, so check the current rules with a lender or the program’s official site.
4. Buying a House Beyond Your Budget
Buying a house beyond your budget usually starts with a preapproval figure being treated as a target. A lender checks whether you qualify. It does not check whether you will feel comfortable. Lenders look closely at your debt to income ratio, which compares your monthly debt payments to your monthly gross income, but it ignores things like childcare, commuting, savings goals and how stable your job feels.
Here is an illustration. Suppose your gross income is $6,000 a month, and you pay $600 a month toward a car and student loans. A home with a total housing payment of $1,900 would put your debts plus housing at $2,500, which is about 42 percent of your income before tax. A lender may allow that. You might still find it tight once utilities, food and savings come out of take home pay.
A safer method is to start from your real monthly spending, decide the payment you can carry comfortably, and work backwards to a price. Then treat the lender’s maximum as a ceiling, not a goal.
Next step: Write down your monthly take home pay and every regular expense, then decide the housing payment you would be comfortable with before you talk about price.
Mistakes With the Full Cost of Buying
1. Forgetting Cash to Close
Your down payment is only part of the money you need on closing day. Closing costs include lender fees, title and appraisal charges, prepaid taxes and insurance, and more. They are often quoted as a few percent of the loan, but the amount varies by state and lender, so rely on your Loan Estimate instead of a rule of thumb.
This illustration uses a $300,000 home and assumes 5 percent down, closing costs of 3 percent of the price, and small allowances for moving and setup. Every figure is an assumption, not a market average.
| Item (illustrative) | Amount |
| Down payment, 5 percent of $300,000 | $15,000 |
| Closing costs, assumed 3 percent of price | $9,000 |
| Moving costs, assumed | $1,500 |
| Immediate setup and small repairs, assumed | $2,000 |
| Total cash needed | $27,500 |
Earnest money, the deposit you pay when your offer is accepted, is normally credited toward these costs at closing, so it is not an extra on top. It can be at risk if you back out for reasons your contract does not allow.
2. Ignoring the Costs of Owning
A mortgage payment is not the whole monthly cost. Property taxes and homeowners insurance are often folded into the payment through an escrow account, and both can rise. If the home is in a community with an association, add its dues. Then add maintenance, which many owners plan as a yearly percentage of the home’s value.
Do not assume your parents’ costs or a neighbor’s costs match yours. Ask for the actual tax bill, request insurance quotes before you make an offer, and check whether the home sits in a flood zone, since flood coverage is usually separate.
The mortgage interest rate matters too. Using the $285,000 loan from the example above (the $300,000 price minus $15,000 down) over 30 years with a fixed rate, the principal and interest payment differs noticeably between two rates. The figures are illustrations and exclude taxes, insurance and mortgage insurance.
| Rate (illustrative) | Monthly principal and interest | Total paid over 30 years |
| 6 percent | $1,708.72 | about $615,100 |
| 7 percent | $1,896.11 | about $682,600 |
| Difference | $187.39 a month | about $67,500 |
One percentage point changes the payment by roughly $187 a month in this example, which is why comparing lenders can pay off.
3. Draining Your Savings
Using every dollar for the down payment feels responsible until the water heater fails in month two. Keep an emergency fund that stays untouched. A common guideline is three to six months of essential expenses, and for a household spending $3,000 a month that would be $9,000 to $18,000. Keep this reserve separate from your cash to close, and add it to your savings target.
Mistakes While House Hunting
1. Letting Emotion Make the Decision
A staged kitchen can make a weak house feel perfect. Before viewing homes, write two lists. Needs are things you cannot live without, such as commute length, bedrooms or accessibility. Wants are nice extras, such as a bigger yard. Judge each home against the needs list first and be willing to compromise on the wants.
Be flexible about the finish, not the structure. Paint and fixtures are cheap to change. Layout, roof condition and neighborhood are not.
2. Overlooking Location and Resale Value
You are buying the surroundings as well as the building. Visit at different times of day, check commute times, noise, flood and crime information from official sources, school quality if it matters to you, and plans for new development nearby. Think about whether the home would still suit you in five to seven years, because selling soon after buying can cost more than staying.
Also look at nearby sale prices. An unusual home may be hard to value, and overpaying for upgrades that the neighborhood does not support is a common regret.
3. Waiving or Rushing the Inspection
In a competitive market it can be tempting to skip the home inspection to make an offer stronger. That can leave you with problems in the roof, wiring, plumbing or foundation, and you would own all of them. An inspection costs a small fraction of a major repair. Use the report to ask for repairs, a lower price or a credit, and consider specialist checks for sewer lines, radon or pests where relevant.
Remember the difference between an inspection and an appraisal. An inspection is for you, to learn the home’s condition. An appraisal is for the lender, to confirm that the home supports the loan amount.
Mistakes Between Offer and Closing
4. Changing Your Finances Before Closing
Lenders may check your credit and employment again shortly before closing. A new car loan, a new credit card, a job change, or a large unexplained deposit can change the numbers and even cancel the approval.
- Hold credit steady. Do not open or co sign any new debt.
- Keep income stable. Tell your lender before you change jobs or income.
- Document large deposits. Gifts and transfers need documents, so ask your lender how to handle them.
- Wait to spend. Delay big purchases, such as furniture, until after you have the keys.
5. Not Understanding Rate Locks and Loan Documents
Rates can move while your loan is processed. A rate lock holds the quoted rate for a set period, and some lenders charge for longer locks or for extensions if closing is delayed. Ask what the lock covers, how long it lasts and what happens if it runs out.
Read the Loan Estimate you receive after applying, then compare it with the Closing Disclosure, which lenders must provide at least three business days before closing. Look for changes in the rate, the loan amount and the fees. If something looks different, ask about it now, not at the signing table.
From Preapproval to Closing: A Simple Timeline
| Stage | What to do |
| Before shopping | Check credit, set a budget, save for cash to close and reserves |
| Preapproval | Compare lenders, get a preapproval letter, and keep the paperwork ready |
| Searching | View homes against your needs list, check taxes and insurance costs |
| Offer accepted | Pay earnest money, order the inspection, finish the loan application |
| Underwriting | Respond quickly to document requests, keep finances unchanged |
| Final week | Compare the Closing Disclosure with the estimate, do a final walkthrough |
| Closing | Bring identification and funds, sign, and collect the keys |
Quick Readiness Checklist
- You know your credit status and have fixed any errors.
- You have a payment you would be comfortable with, not just a lender’s maximum.
- Your savings cover cash to close and a separate emergency fund.
- You have compared at least two lenders on rate and fees.
- You have asked about assistance programs and low down payment loans.
- You plan to inspect the home and review the documents carefully.
Next step: Look into a HUD approved housing counselor if you want free or low cost guidance. The CFPB and HUD sites listed below are good places to begin.
Conclusion
Most first time home buyer mistakes come down to timing and assumptions: checking credit too late, trusting the maximum a lender offers, and forgetting what happens after closing. The good news is that nearly all of them can be avoided with a few months of preparation and honest numbers. Before you tour a single home, decide on a payment you can live with, build a cash cushion and compare more than one lender. A calm, prepared buyer almost always makes a better decision than a rushed one.
Frequently Asked Questions
What is the biggest mistake first-time home buyers make?
Buying at the maximum amount the lender approves. Lenders qualify you on gross income without accounting for your lifestyle, savings goals, or surprise repair bills — so the “approved” number usually stretches you thinner than is comfortable. Set your budget from your actual monthly finances, not the bank’s ceiling.
How much should I save before buying my first home?
Beyond the down payment, plan for 2–5% of the price in closing costs and keep a 3–6 month emergency fund intact after closing. Draining every dollar to get the keys leaves you one broken furnace away from credit-card debt.
Do I need a 20% down payment to buy my first home?
No. Conventional loans go as low as 3% down and FHA loans 3.5% for qualified buyers. Putting down less than 20% usually means paying private mortgage insurance, but waiting years to save 20% while prices and rates move can cost more than the PMI itself.
Should I wait for mortgage rates to drop before buying?
Timing the market perfectly is nearly impossible, and waiting has its own cost if prices keep rising. Buy when your savings, credit, and job situation are ready — if rates fall later, refinancing is always an option.
What are closing costs for a first-time buyer?
Typically 2–5% of the purchase price: lender fees, appraisal, title insurance, and prepaid taxes and insurance. They are due at closing on top of the down payment, so budget for them from the start rather than discovering them weeks before closing day.
Should I get pre-approved before house hunting?
Yes. Pre-approval tells you your realistic budget, surfaces credit issues while there is still time to fix them, and makes your offers credible to sellers. Just remember a pre-approval is a ceiling, not a target — you do not have to spend it all.